

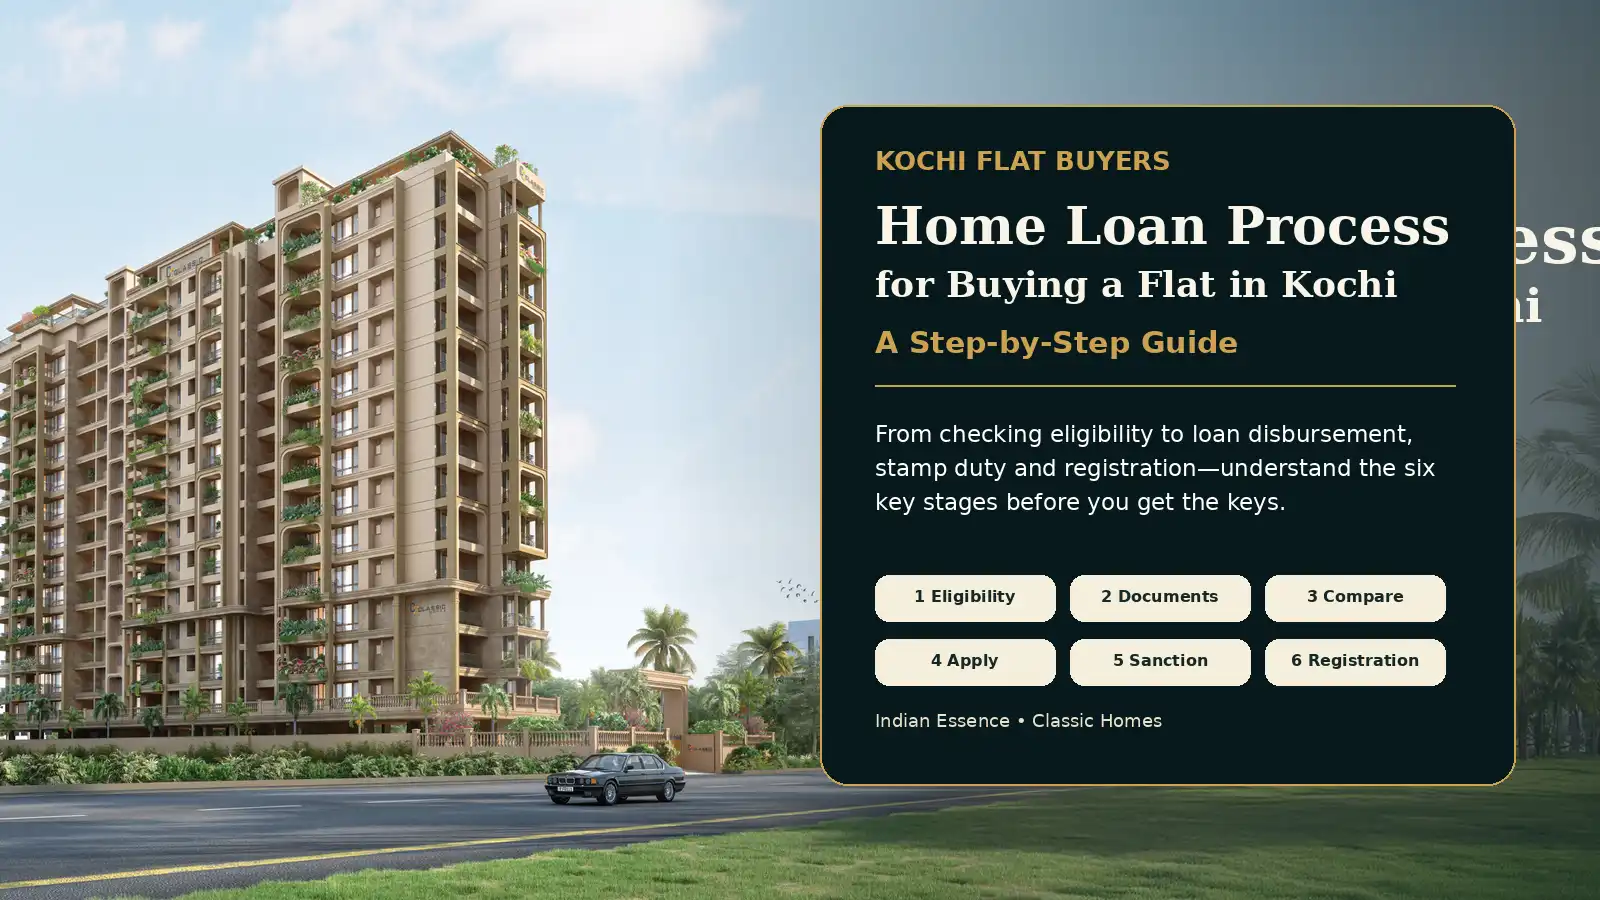
Right up the paperwork begins while buying a flat in Kochi, the excitement turns into a pile of forms, bank visits and questions nobody warned you about. If this situation feels all too familiar, take a moment to pause and breathe. The home loan process, first time Kochi Flat buyers go through is straightforward once you know the steps in order.
This guide walks you through each stage from checking your eligibility to collecting your keys.
Why the Home Loan Process Kochi Flat Buyers Follow Matters
Kochi's property market has grown fast. New apartment projects keep coming up in and around the city especially Kakkanad, Edappally and Vyttila areas. With so many banks and NBFCs competing for their business, the home loan process can feel confusing. But a bit of preparation saves you weeks of back and forth with your lender while following Home Loan Process for Kochi Flat.
As of August 2026, the RBI has kept the policy repo rate unchanged at 5.25% for the fourth consecutive meeting. That means home loan interest rates have stayed fairly steady in recent months, giving buyers a more predictable window to plan their EMIs. Stability like this is good news if you're finalising your budget for a flat purchase this year.
Step 1: Check Your Home Loan Eligibility
Before you fall in love with a flat, check what you can actually borrow. Lenders look at your income, age, existing debts and repayment capacity. A steady salary or business income improves your chances. So does a clean repayment history.
Your CIBIL score plays a big role here too. Most banks want a score above 700 for the best terms. If yours is lower, work on it before you apply. Pay off small debts and clear any overdue bills first.
Step 2: Gather Your Home Loan Documents
Paperwork trips up more buyers than anything else. Keep these ready before you approach a lender:
- Identity and address proof
- Income proof (salary slips or ITR for the last three years)
- Bank statements for six months
- Property documents from the builder or seller
- Passport size photographs
Self employed buyers also need business proof and profit loss statements. Missing even one document can delay your home loan process application by days.
Step 3: Compare Home Loan Interest Rates and Lenders
Don't walk into the first bank branch you see. “Interest rates, processing charges, and prepayment conditions differ from one lender to another. A floating rate home loan changes with market conditions while a fixed rate loan remains unchanged for a specified period. Each has trade offs worth understanding.
Ask about processing charges, legal fees and any hidden costs. A slightly lower interest rate with high fees might cost you more over time. Take your time here. It's one decision that shapes your finances for years.
Step 4: Submit Your Application and Property Papers
Once you pick a lender, submit your loan application along with the flat's title deed, sale agreement and approved building plan. The bank will also want an occupancy certificate if the project is complete.
The lender then arranges a technical and legal check on the property. This confirms the builder holds clear title and the project has proper approvals. For under construction flats, banks also verify RERA registration before moving forward.
Step 5: Loan Sanction and Property Valuation
If everything checks out, the bank issues a loan sanction letter. This document states your approved loan amount, interest rate and tenure. Read it carefully before signing anything.
Alongside this, the bank conducts a property valuation to confirm the flat's market worth matches the purchase price. Banks typically fund 75 to 90 percent of the property value, so your down payment covers the rest.
Step 6: Disbursement, Stamp Duty and Registration
Once you sign the loan agreement, the bank moves to home loan disbursement. For ready flats, the full amount goes to the seller in one go. For under construction projects, disbursement happens in stages tied to construction progress.
Remember to budget separately for stamp duty and registration charges in Kerala. These costs sit outside your loan amount and need to be paid from your own pocket at the time of registration.
Common Mistakes to Avoid
Many first time buyers rush this process and pay for it later. Watch out for these slip ups:
- Applying to multiple banks at once which can hurt your credit score
- Ignoring the fine print on prepayment penalties
- Skipping a legal check on the property title
- Underestimating registration and other closing costs
- Not comparing the total EMI outgo across lenders
Slow down at each step. A few extra days of checking now can save you months of stress later.
Let Classic Homes Simplify Your Home Loan Process
Here's something most buyers don't know. Classic Homes offers an in-house housing finance assistance service for its projects across Kochi. Their team helps with documentation, banker selection and approvals, so you don't have to chase paperwork on your own.
If you're eyeing a flat in Kochi with Classic Homes, this support can shave weeks off your home loan process journey. From picking the right lender to smoothing out approval hurdles, having someone in your corner makes the whole experience less stressful.
Final Thoughts
Getting a home loan doesn't have to feel like a maze. Break it into these six steps, keep your documents ready and compare lenders before you commit. With repo rates holding steady this year, now is a reasonably stable time to plan your purchase.
And if you'd rather not handle the banking maze alone, reach out to Classic Homes for guided support through every stage, from eligibility to registration.